Portfolio Attribution Analysis: Measuring What Really Drives Returns
Published on 20 Oct, 2026
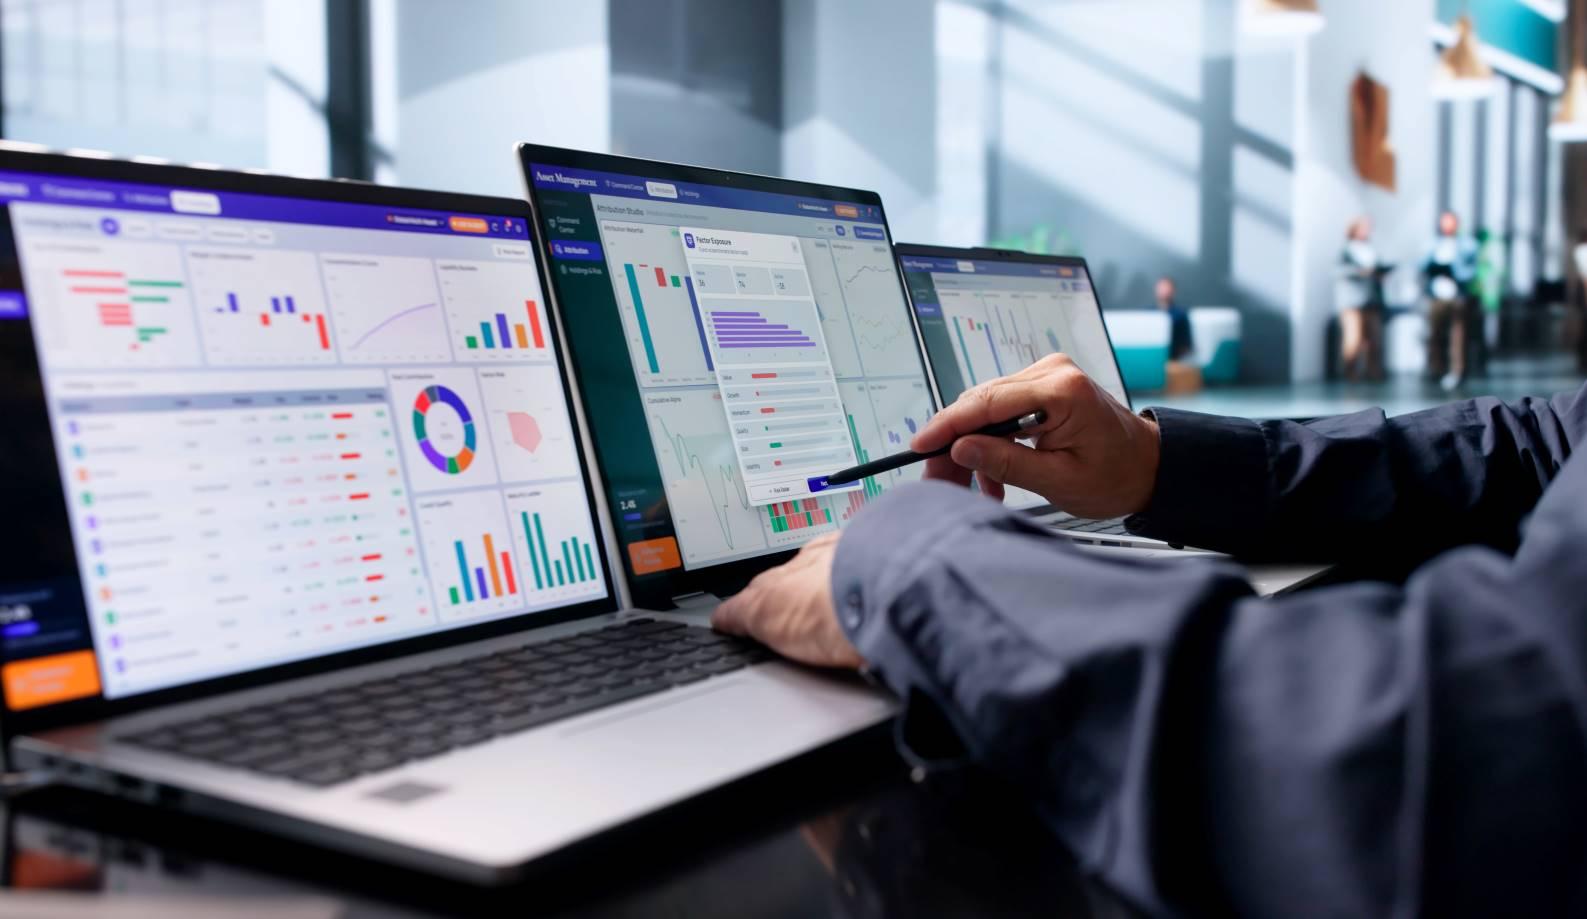
Knowing that a portfolio outperformed or underperformed its benchmark is only the beginning of the story. Institutional investors, portfolio managers, and investment committees need to understand precisely why that outcome occurred: was it driven by sector allocation, security selection, currency exposure, or simple market beta? Answering this question reliably requires a disciplined analytical process known as portfolio attribution analysis.
Portfolio attribution analysis decomposes total portfolio returns into their underlying components, isolating the specific decisions and exposures responsible for performance relative to a benchmark. Rather than treating performance as a single, undifferentiated number, attribution analysis provides the granular insight needed to distinguish genuine skill from market luck, and to identify which parts of an investment process are adding value.
For institutional investors managing fiduciary responsibilities and reporting obligations to clients and boards, robust performance attribution is not simply a reporting exercise; it is a critical feedback loop that informs manager evaluation, strategy refinement, and capital allocation decisions. This article explores the core methodologies behind portfolio attribution analysis, how institutional investors apply it in practice, and best practices for building a reliable attribution process.
What Is Portfolio Attribution Analysis?
Portfolio attribution analysis is the process of breaking down a portfolio's total return relative to a benchmark into distinct components, typically including asset allocation, security selection, and interaction effects. This decomposition allows investors to understand precisely which decisions contributed positively or negatively to relative performance over a given period.
This analysis serves multiple purposes within an institutional investment process. It supports internal performance evaluation of portfolio managers and investment teams, provides transparency for client and board reporting, and generates insights that can refine future investment decisions by identifying which aspects of a strategy are genuinely adding value versus detracting from it, forming a core part of ongoing investment performance analysis.
Core Methodologies in Portfolio Attribution Analysis
Several established methodologies are used to conduct portfolio attribution analysis, each suited to different portfolio structures and investment strategies.
1. Brinson Attribution
The Brinson model, one of the most widely used attribution frameworks, decomposes active return into allocation effect, selection effect, and interaction effect. Allocation effect measures the impact of overweighting or underweighting specific sectors or asset classes relative to the benchmark, while selection effect measures the impact of security selection within those sectors.
2. Factor-Based Attribution
Factor-based attribution decomposes returns based on exposure to specific risk factors, such as value, momentum, quality, or size, rather than sector or geographic allocation alone. This approach is particularly useful for quantitative strategies or portfolios where factor exposures, rather than discretionary sector bets, are the primary driver of returns.
3. Fixed Income Attribution
Fixed income portfolios require specialized attribution approaches that account for duration positioning, yield curve exposure, credit spread decisions, and currency effects, since these factors interact differently than the sector and stock-level decisions relevant to equity attribution.
4. Multi-Period Attribution
Since single-period attribution results can be affected by timing and compounding effects, multi-period attribution methodologies link results across multiple periods to provide a more accurate, cumulative view of how specific decisions contributed to performance over longer time horizons.
5. Currency Attribution
Isolates local market performance, currency exposure and hedging decisions. The Karnosky–Singer framework separates market and currency decisions while accounting for interest-rate differentials.
How Institutional Investors Use Portfolio Attribution Analysis?
Institutional investors apply attribution analysis across several key functions. Investment committees use attribution results to evaluate whether portfolio managers are generating value through genuine skill in sector allocation or security selection, rather than simply benefiting from broad market movements.
Attribution analysis also informs manager selection and due diligence for allocators evaluating external investment managers, providing insight into whether a manager's stated investment process is actually reflected in their realized performance drivers. For internal teams, attribution results create a feedback loop that helps refine investment processes, informing decisions such as whether to expand successful strategies or curtail approaches that have not added consistent value, supported by thorough portfolio performance and risk analysis.
Common Challenges in Portfolio Attribution Analysis
Despite its analytical value, building and maintaining a reliable attribution process presents several practical challenges for institutional investors.
- Selecting the appropriate attribution methodology for complex, multi-asset, or alternative strategy portfolios
- Ensuring data quality and consistency across custodians, benchmarks, and internal systems
- Accurately capturing the impact of currency hedging and derivative overlays on attribution results
- Distinguishing genuine skill from statistical noise, particularly over shorter measurement periods
- Communicating complex attribution results clearly to clients, boards, and non-technical stakeholders
Best Practices for Building a Reliable Attribution Process
Institutions can strengthen their portfolio attribution capabilities through several practical measures focused on methodology selection, data quality, and consistent application.
- Selecting an attribution methodology that genuinely matches the portfolio's investment strategy and asset classes
- Maintaining rigorous data governance to ensure consistency between attribution inputs and actual portfolio holdings
- Conducting attribution analysis across multiple time periods to distinguish persistent skill from short-term noise
- Supplementing internal capabilities with specialized portfolio analytics services for complex or multi-asset mandates
- Translating attribution findings into clear, actionable insights for both internal teams and external stakeholders
Why Portfolio Attribution Analysis Matters for Institutional Decision-Making?
Beyond its reporting function, portfolio attribution analysis plays a central role in disciplined investment decision-making. By clearly identifying which decisions and exposures are actually driving returns, attribution analysis helps investment teams allocate research resources toward the strategies and processes that demonstrate genuine, repeatable value.
This discipline is particularly important for institutional investors managing multiple strategies or external manager relationships, where attribution analysis provides an objective basis for capital allocation decisions rather than relying solely on headline performance figures that may mask significant underlying variability in skill and process quality.
Conclusion
Portfolio attribution analysis provides institutional investors with the granular insight needed to understand what is truly driving portfolio performance, moving beyond simple return figures to isolate the specific decisions and exposures responsible for outcomes relative to a benchmark. By applying rigorous, methodology-appropriate attribution analysis, investors can distinguish genuine skill from market luck and make more informed decisions about strategy allocation and manager evaluation.
As portfolios grow more complex across asset classes and strategies, disciplined performance attribution is becoming an increasingly essential tool for institutional investors seeking accountability and continuous improvement in their investment processes.
Partnering with an experienced investment research provider can help institutional investors build a robust attribution analysis capability that supports clearer reporting and more disciplined investment decision-making.